
TRW & Co · Banking, Finance & Capital Markets
Trade Finance in the UAE
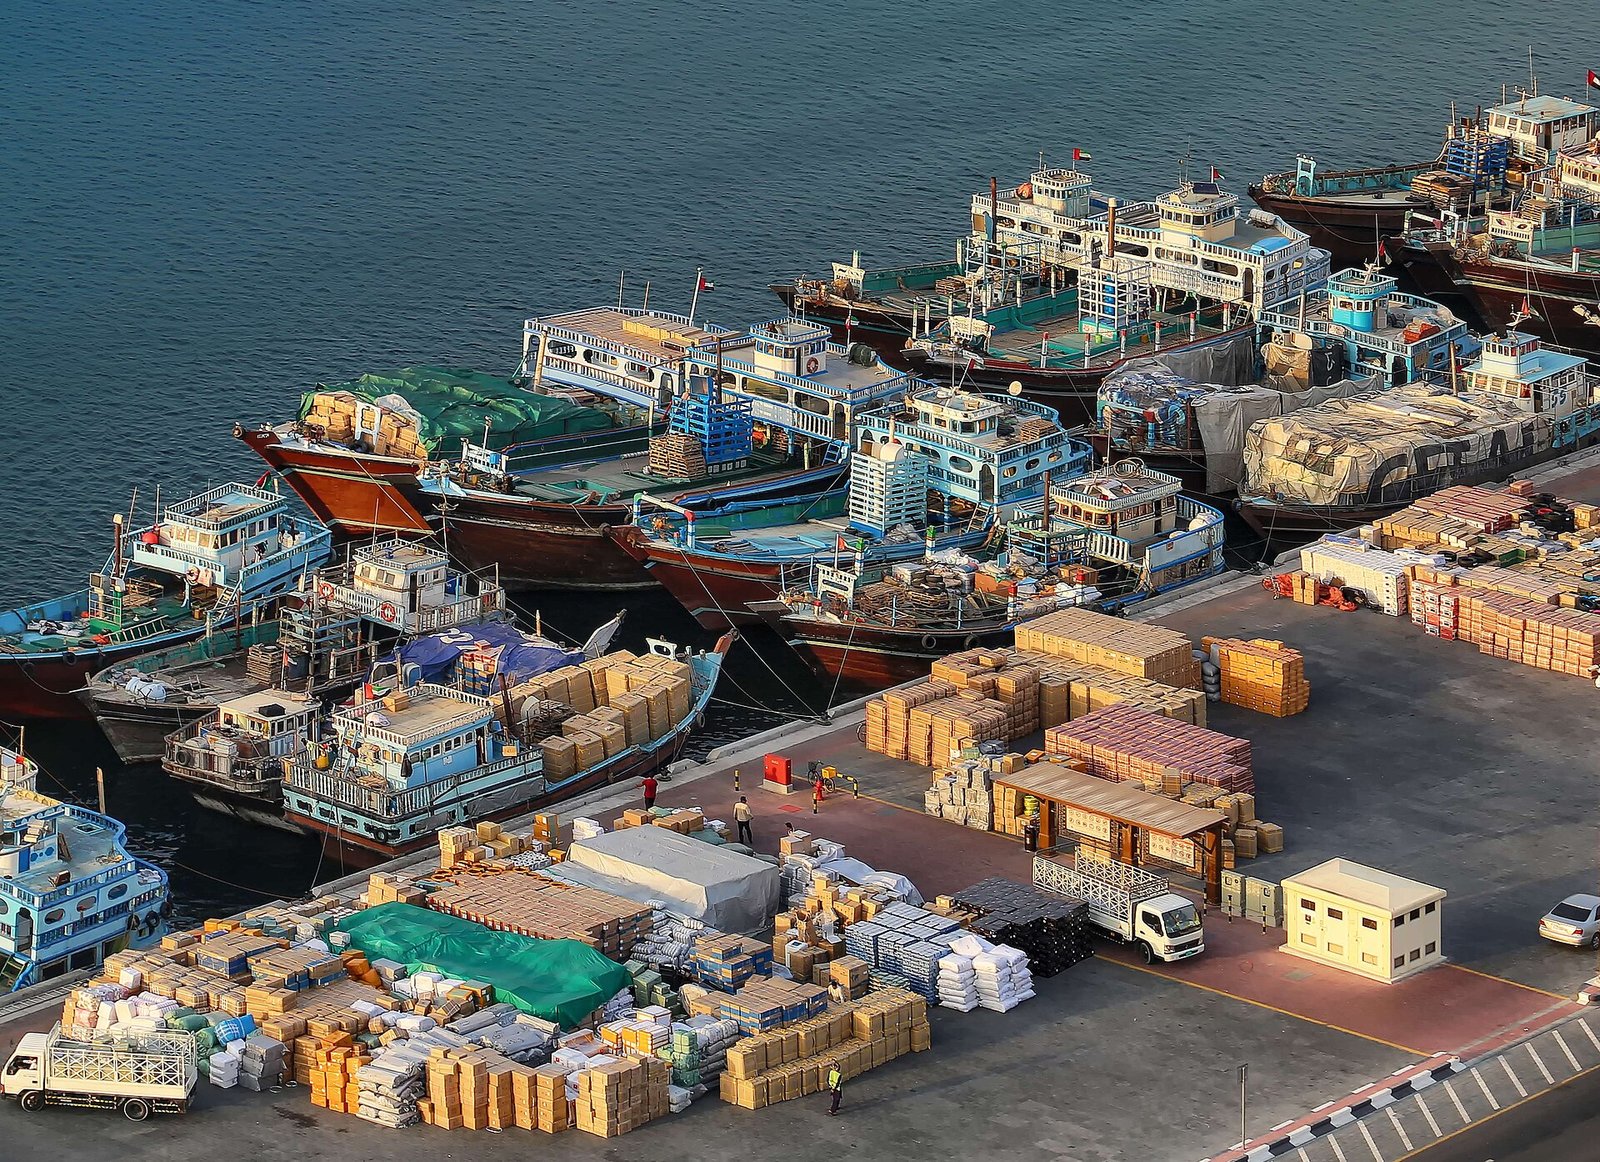
Trade finance in the UAE funds the goods moving through one of the world's busiest re-export hubs. Banks, traders and exporters rely on letters of credit, guarantees and receivables facilities, but their protection depends on precise documents, registered security and careful sanctions screening. This guide explains the law, the instruments and the decisions that matter.
Key pointHolding shipping documents is not the same as holding security: under Federal Law No. 4 of 2020, a lender's interest in goods, receivables and accounts generally needs a registered notice or control agreement to bind third parties and rank in insolvency.
At a glance
Commercial Transactions Law
Federal Decree-Law No. 50 of 2022, in force since 2 January 2023, governs banking operations including documentary credits and guarantees and recognises the ICC's uniform customs.
Registered movable security
Security over inventory, receivables and accounts is perfected by registration in the Emirates Movable Collateral Registry or, for accounts, by a control agreement.
Autonomy of instruments
Credits and demand guarantees are paid on compliant documents or demands; courts stop payment only on clear evidence of fraud, so applicants must act very quickly.
Five-year limitation
Claims between merchants are generally time-barred five years after performance fell due, halving the ten-year period that applied under the 1993 Commercial Code.
Sanctions and TBML focus
Banks screen parties, goods, vessels and routes, and the Central Bank issued guidance in November 2025 on trade-based money laundering and transshipment risk.
Swipe or scroll →
What trade finance in the UAE covers
Trade finance in the UAE is the body of banking products, contracts and security that funds and protects the movement of goods into, out of and through the Emirates: documentary credits, standby letters of credit, demand guarantees, documentary collections, pre-export and inventory finance, receivables discounting, supply chain finance and structured commodity finance. It concerns traders, manufacturers, commodity houses, logistics groups, the banks that finance them and the insurers that cover their risk.
The UAE is one of the world's busiest re-export hubs. Goods arrive at Jebel Ali, Khalifa Port or Sharjah, change hands in free zones and leave for the GCC, South Asia, Africa and Central Asia, often financed by several banks along the way. That makes the legal questions practical and immediate: will this credit be honoured, can this guarantee be stopped, does the bank actually have security over the cargo or the receivables, and what happens when a buyer, a bank or a vessel is sanctioned?
Trade finance in the UAE becomes a legal question at three moments: when the instrument and security are structured, when documents are presented and refused or a guarantee is called, and when a counterparty defaults or a fraud surfaces. Each has its own rules and its own short deadlines.
The legal and regulatory framework
The Commercial Transactions Law
The core onshore statute is Federal Decree-Law No. 50 of 2022 on Commercial Transactions, which came into force on 2 January 2023 and replaced the 1993 Commercial Code. It regulates banking operations, including documentary credits, bank guarantees, current accounts and commercial loans, and recognises the International Chamber of Commerce's uniform customs for documentary credits. In practice, UAE banks expressly incorporate UCP 600 for credits and URDG 758 or ISP98 for guarantees and standbys, and well-drafted instruments always do.
Several provisions matter directly to trade finance in the UAE. Where a commercial loan agreement does not fix an interest rate, the fallback cap is 9%, and Article 88 prohibits compound interest. Article 409 requires banks to obtain sufficient security for commercial loans. Claims between merchants are generally time-barred five years after performance fell due, down from ten years under the old law. Part 6 adds rules for Islamic financial institutions, covering murabaha, istisna'a, ijarah and salam contracts that underpin much Islamic trade finance.
Security over goods, receivables and accounts
Federal Law No. 4 of 2020 on Securing Rights over Movable Property, with its executive regulations in Cabinet Resolution No. 29 of 2021, allows security over present and future movables, including inventory, goods in transit, receivables and bank accounts, and extends automatically to proceeds unless the parties agree otherwise. Security becomes effective against third parties by registering a notice in the Emirates Movable Collateral Registry, and priority generally follows the time of registration. Bank accounts are perfected by a control agreement, which ranks ahead of competing interests other than the account bank's own.
Enforcement can be out of court after formal notice to the debtor and security provider, or through the urgent matters judge, who decides applications within five working days and may act without notice to the other side. Assets registered in a special registry, such as vessels and vehicles, follow their own rules.
Regulators, courts and wider law
Banks are licensed by the Central Bank of the UAE under Federal Decree-Law No. 6 of 2025. Anti-money laundering duties come from Federal Decree-Law No. 10 of 2025 and its executive regulations, and targeted financial sanctions are administered through the Executive Office for Control and Non-Proliferation.
In November 2025 the CBUAE issued guidance to licensed financial institutions on trade-based money laundering and transshipment risk. General contract rules come from the new Civil Transactions Law, Federal Decree-Law No. 25 of 2025, in force from 1 June 2026. The DIFC and ADGM apply their own contract, security and insolvency laws, regulated by the DFSA and the FSRA, and their own courts hear disputes that fall within their jurisdiction.
| Instrument | Typical rules | Who bears the risk | Key legal point |
|---|---|---|---|
| Documentary credit (LC) | UCP 600, eUCP for electronic presentation | Issuing bank, and confirming bank if confirmed | Payment depends on complying documents, not the underlying sale |
| Standby LC | ISP98 or UCP 600 | Issuing bank | Functions as a guarantee; drafting of the demand condition is critical |
| Demand guarantee | URDG 758 or bespoke terms | Issuing bank, backed by counter-indemnity | Autonomous from the underlying contract; stopping a call needs clear fraud or abuse |
| Documentary collection | URC 522 | Seller, until buyer pays or accepts | Banks act as agents only and do not guarantee payment |
| Receivables finance and supply chain finance | Contract, Civil Transactions Law, Movables Law | Financier, subject to recourse terms | Assignment notice, registration and anti-assignment clauses decide enforceability |
| Islamic trade finance (murabaha, wakala) | Commercial Transactions Law Part 6, Shari'ah rulings | Financier owns or controls goods briefly | Asset ownership steps must actually happen to be valid |
Key decisions in structuring a facility
Choosing the instrument
A confirmed letter of credit gives the exporter the strongest payment protection but costs more and demands disciplined documentation. Open account trade with credit insurance or receivables finance is cheaper and faster but leaves more credit risk. For contracts with performance obligations, such as supply and installation, demand guarantees and standbys are the norm. The choice should follow the counterparty's credit, the country risk and the seller's ability to produce compliant documents on time.
Building the security package
Lenders should not assume that holding documents of title equals security. Onshore, take and register security over inventory, receivables and collection accounts under the Movables Law, and use control agreements for accounts. Where goods sit in a free zone warehouse, check the warehouse's rules and the collateral manager's agreement. For receivables, review buyer contracts for anti-assignment and set-off clauses and plan notice to buyers.
Governing law and forum
Many facility agreements choose English law with DIFC Courts, ADGM Courts or arbitration (for example under DIAC rules). The instrument itself, the security and enforcement against UAE assets will still engage UAE law. Align the forum with where assets and counterparties are, and remember that security over onshore assets must comply with onshore formalities whatever the facility's governing law.
Credit insurance and export credit support
Etihad Credit Insurance, the UAE's federal export credit company, offers trade credit and political risk insurance, surety bonds and trade finance support such as invoice discounting, supply chain finance and LC confirmation cover. Private credit insurance is also widely used. Read policy conditions carefully: notification deadlines, credit limits and exclusions decide whether a claim pays.
Trade finance in the UAE rewards precision. A discrepancy in a bill of lading, an unregistered security notice or an unscreened vessel can turn a secured, paid transaction into a contested loss.
The transaction lifecycle step by step
- Onboard and screen. The bank runs KYC on the applicant, the counterparty and, increasingly, the goods, vessels, ports and routes, applying its trade-based money laundering and sanctions controls.
- Agree the facility and security. Sign the facility letter or agreement, counter-indemnities, and security over goods, receivables and accounts; register notices in the movable collateral registry.
- Issue the instrument. The bank issues or advises the credit or guarantee on agreed wording, incorporating UCP 600, URDG 758 or ISP98 as appropriate.
- Ship and present. The beneficiary ships and presents documents within the credit's validity and presentation period; the bank has a maximum of five banking days after presentation to examine them under UCP 600.
- Pay, refuse or negotiate. A complying presentation must be honoured. A refusal must be given in a single notice listing every discrepancy within the examination period, or the bank may lose the right to refuse.
- Manage claims and calls. For guarantees, the beneficiary makes a demand complying with the guarantee's terms; the applicant has limited time to seek any injunction.
- Collect and reconcile. Proceeds flow to collection accounts, the facility is repaid and security released, or recovery begins if the counterparty defaults.
Documents and evidence to assemble
Most trade finance in the UAE disputes are won or lost on paper. Keep a complete file for every transaction:
- the sale contract, purchase orders, pro forma invoices and any amendments;
- the credit or guarantee text, every amendment and the governing rules incorporated;
- transport documents (bills of lading, air waybills), commercial invoices, packing lists, certificates of origin, inspection and insurance certificates;
- bank correspondence, presentation schedules, refusal notices and waiver requests, with timestamps;
- the facility agreement, counter-indemnities, security documents and registry confirmations;
- KYC and screening records, including vessel, port and end-user checks;
- credit insurance policies, declarations and notifications of overdue amounts.
Risks and common mistakes
Trying to stop payment under a letter of credit or guarantee
Credits and demand guarantees are autonomous: the bank pays against compliant documents or a compliant demand, regardless of disputes about the underlying goods or works. UAE onshore courts and the DIFC and ADGM Courts recognise a fraud exception but apply it narrowly. A quality dispute, delay or breach of contract is not enough; clear evidence of fraud connected to the demand is needed, and courts act quickly. An applicant that wants to resist a call must move within days, assemble evidence before the demand arrives and consider whether the guarantee's own terms give a better defence.
Discrepant documents and late refusals
Small inconsistencies between the invoice, the transport document and the credit are the most common reason for non-payment. Beneficiaries should check documents against the credit before shipment, not after. Issuing banks face the mirror-image risk: under UCP 600 a refusal notice must state every discrepancy and be sent within the examination period, and a defective notice can leave the bank obliged to pay. Use checklists and keep timestamped records of presentation and refusal.
Unperfected security over goods and receivables
Lenders sometimes rely on possession of documents, a negative pledge or an unregistered pledge. Under the Movables Law, security generally needs a registered notice to bind third parties and to rank against other creditors, and accounts need a control agreement. Without them a lender may rank as unsecured in a restructuring or bankruptcy under Federal Decree-Law No. 51 of 2023. Register promptly, describe collateral accurately and refresh registrations when facilities are amended.
Sanctions, dual-use goods and transshipment
The UAE's position as a re-export hub makes it a focus for international sanctions enforcement. Banks screen not only parties but goods, vessels, ports and routes, and they will refuse or freeze transactions that touch listed persons or suspicious transshipment patterns. Exporters should expect enhanced questions about end users and dual-use goods. Build sanctions clauses that allow a bank to refuse lawfully without breaching the credit, and check exposure under UAE, UN, US, UK and EU regimes.
Fraudulent or duplicate financing
Commodity and receivables fraud often involves the same goods or invoices financed by several banks, fictitious warehouse receipts or collusive buyers. Lenders should verify goods through independent collateral managers, confirm receivables directly with buyers where possible, search the movable collateral registry before lending and monitor concentration. When fraud surfaces, act fast: freezing orders, criminal complaints and claims against insurers each have their own requirements and timing.
Before shipping under a letter of credit, send the full credit text to whoever prepares your documents and ask them to flag every requirement you cannot meet exactly. Amending a credit before shipment costs a fee; discovering a discrepancy after shipment can cost the whole payment.
Disputes, recovery and enforcement
When trade finance in the UAE goes wrong, the route depends on the instrument and the forum. A bank that wrongfully refuses a compliant presentation can be sued for the credit amount. A beneficiary of a guarantee that is not paid can sue the issuing bank. Applicants who claim a call was fraudulent seek urgent injunctions, and banks seek recovery from applicants under counter-indemnities and security.
Onshore claims go to the Dubai Courts, the Abu Dhabi Judicial Department or the federal courts under the Civil Procedure Law, Federal Decree-Law No. 42 of 2022, which also provides fast-track payment orders for liquidated debts. Facilities that choose the DIFC or ADGM Courts, or arbitration, follow those procedures, and judgments and awards then need enforcement against onshore assets.
Cheques given as security remain common; following reforms that took effect in 2022, most returned-cheque matters are pursued through civil execution rather than criminal complaint. Insolvency of a counterparty triggers the procedures and stays under Federal Decree-Law No. 51 of 2023, which is why perfected security matters.
Speed shapes outcomes. Precautionary attachments over a debtor's goods, bank balances or receivables can be sought before or alongside a claim, but courts expect evidence of a genuine debt and a real risk of dissipation, and the applicant may need to start the main proceedings within a short period. Banks pursuing recovery should gather facility documents, statements of account and security registrations in Arabic-ready form at the outset, because translation and attestation often take longer than the legal drafting.
Cross-border angle
UAE trade corridors run strongly to India, China, Bangladesh, Saudi Arabia and Africa. Exports to Bangladesh are often paid by letters of credit issued by Bangladeshi banks under Bangladesh Bank's foreign exchange rules, and UAE sellers should check the issuing bank's standing and consider confirmation. Chinese suppliers and UAE buyers frequently use Chinese banks' credits under UCP 600, and disputes may involve PRC courts' approach to fraud injunctions. Indian corridors raise questions about rupee settlement and Reserve Bank of India requirements.
Many facilities are governed by English law and refer disputes to London or to the DIFC or ADGM Courts, while Singapore law and SIAC arbitration are common for Asian commodity trades. The UAE is a party to the New York Convention, so foreign arbitral awards can be enforced onshore subject to its grounds. Plan forum, governing law and security together so that a favourable judgment can actually reach the assets.
How TRW & Co helps with trade finance in the UAE
We advise banks, traders, exporters and investors on structuring, documenting and enforcing trade finance in the UAE, and coordinate with our Dhaka, Chattogram, Singapore and London teams on the other side of the corridor. Where representation before UAE onshore courts or the DIFC/ADGM Courts is required, we work alongside locally licensed advocates and registered practitioners.
Facility and instrument drafting
We draft and review facility agreements, credits, standby letters and demand guarantees, aligning them with UCP 600, URDG 758 or ISP98 and with the underlying contract.
Security packages
We design security over inventory, receivables and accounts under the Movables Law, prepare control agreements and coordinate registration and releases.
Sanctions and AML review
We assess transactions, goods and counterparties against UAE and international sanctions, and draft clauses that protect banks and traders when a transaction must stop.
Receivables and supply chain finance
We structure receivables purchase, factoring and supplier finance programmes, addressing assignment, set-off, true-sale and accounting questions.
Guarantee calls and LC disputes
We advise on demands, refusals and injunction strategy, and coordinate urgent applications with local advocates when timing is critical.
Fraud and recovery
We help lenders trace goods and proceeds, preserve assets and pursue counterparties, insurers and guarantors across the UAE and abroad.
Related work often includes banking and finance, secured lending, sanctions and export controls, customs and trade compliance, shipping and maritime and Islamic finance. For a deeper look at documentary credits, read our article on trade finance and letters of credit, and for collateral see taking security over assets.
Checklist for decision-makers
- Is the instrument right for the counterparty and country risk, and does it incorporate the correct ICC rules?
- Have we checked every documentary requirement before shipment?
- Is security over goods, receivables and accounts registered and supported by control agreements?
- Have parties, goods, vessels and routes been screened against all relevant sanctions regimes?
- Do the governing law, forum and security line up with where the assets are?
- Are credit insurance notifications and deadlines diarised?
- Do we have an urgent-response plan for a disputed guarantee call or a discovered fraud?
To discuss trade finance in the UAE for your business, contact our team at info@trw.co, or browse all our practices.
Frequently asked questions
01Which rules govern letters of credit in the UAE?
The Commercial Transactions Law, Federal Decree-Law No. 50 of 2022, regulates documentary credits and recognises the International Chamber of Commerce's uniform customs. In practice, UAE banks expressly incorporate UCP 600, and eUCP where documents are presented electronically. The credit's own terms and the incorporated rules decide most questions, such as examination time, discrepancies and refusal notices. Always check that the credit names the rules expressly, because a credit that does not may be decided under UAE law alone.
02Can I stop a bank paying a guarantee call in the UAE?
Only in narrow circumstances. Demand guarantees and standby credits are independent of the underlying contract, so disputes about performance, quality or delay do not by themselves justify stopping payment. UAE onshore courts and the DIFC and ADGM Courts recognise a fraud exception but require clear evidence. An applicant should review the guarantee wording for any conditions the beneficiary must meet, gather evidence before the call arrives and be ready to apply urgently with local advocates.
03How does a lender take security over goods and receivables?
Under Federal Law No. 4 of 2020 and Cabinet Resolution No. 29 of 2021, the parties sign a security agreement and register a notice in the Emirates Movable Collateral Registry, which makes the security effective against third parties and sets priority. Security can cover future inventory, receivables and proceeds. For bank accounts, a control agreement with the account bank is used. Assets with their own registries, such as ships, follow separate rules.
04What happens if documents are discrepant?
If documents do not comply with the credit, the issuing bank may refuse to pay, but under UCP 600 it must do so in a single notice listing every discrepancy, sent within five banking days after presentation. The applicant may waive the discrepancies, which is common when the goods are wanted. If the bank's refusal notice is defective or late, it may lose the right to refuse. Beneficiaries should check documents carefully before presentation.
05Do Islamic trade finance products work differently?
Yes. Murabaha, wakala and similar structures require the financier to acquire or control goods before selling them on, and Part 6 of the Commercial Transactions Law now sets specific rules for contracts with Islamic financial institutions. The asset steps must actually take place, with documents to prove them, or the transaction may be challenged. Shari'ah supervision applies, and resolutions of the Central Bank's Higher Shari'ah Authority bind institutions' internal committees.
06How long do we have to bring a trade finance claim?
Under the Commercial Transactions Law, claims between merchants are generally time-barred five years after the date performance fell due, shorter than the previous ten-year period. Different periods can apply to specific instruments, consumer matters, claims under foreign law or the DIFC and ADGM regimes, and insurance policies often set much shorter notification deadlines. Diarise limitation dates from the moment a payment is missed.
07Can a UAE exporter get credit insurance or government support?
Yes. Etihad Credit Insurance, the UAE's federal export credit company, offers trade credit and political risk insurance, surety bonds and trade finance support such as invoice discounting and LC confirmation cover. Private insurers also offer credit insurance. Banks often lend more readily against insured receivables. Read policy conditions carefully, because missed notification deadlines and unapproved credit limits are common reasons claims are refused.
Sources and official materials
- Central Bank of the UAE — Bank licensing, AML guidance and trade-based money laundering guidance
- UAE Legislation portal — Commercial Transactions Law and Movables Security Law texts
- Etihad Credit Insurance — Federal export credit insurance and trade finance support
- Executive Office for Control and Non-Proliferation — Targeted financial sanctions and lists
- Dubai International Arbitration Centre — Arbitration rules for trade and banking disputes
- Dubai Financial Services Authority — Regulator of banks and finance providers in the DIFC
General information only, current as at 27 October 2026. It is not legal advice and does not create a lawyer–client relationship. UAE law differs between the onshore jurisdiction, the DIFC, ADGM and the free zones, and changes frequently; check current official sources and take advice on the facts of your matter.



